TD Bank (US)

Screenshots
Details
- Rating
- 33.83K reviews
- Version
- 26.10.1.71
- Developer
- TD Bank, N.A.
Analysis by Norviv
Managing money from a phone sounds simple until a banking app has to work in the middle of a busy day, with a weak signal, a forgotten password, or a payment that needs checking immediately. I spent time using TD Bank as a day-to-day finance app, paying close attention not just to its banking tools but also to how much the experience depends on a reliable connection. My overall impression is that it is a practical mobile companion for TD customers, especially when you want to check an account, move money, or deal with routine banking without opening a laptop.
It is a free app from TD Bank, N.A., aimed at everyday banking and rated for Everyone. Its average rating sits at 4.2 from roughly 90 thousand ratings, and its reach of more than 5 million installs suggests that it has become a familiar option for a large number of customers. That popularity does not make every interaction perfect, though. The app is most comfortable when your phone has a stable connection and you already know what you want to do. If your priority is detailed budgeting, investing, or managing accounts from several banks in one place, you may find a specialist alternative more suitable.
What daily banking feels like when the connection is good
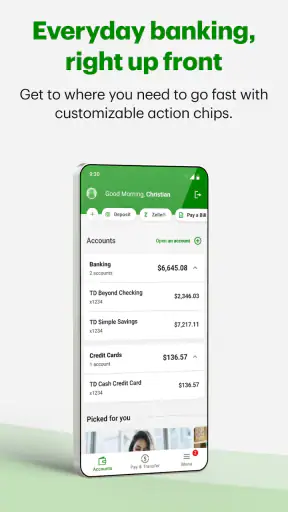
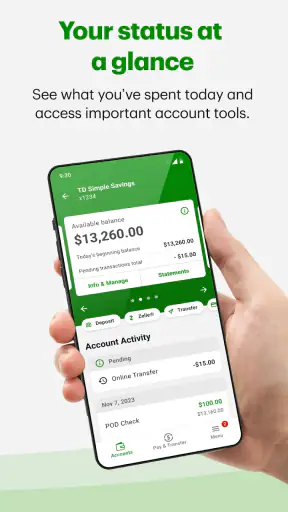
The strongest part of the experience is the way the app brings common banking tasks into one mobile space. Instead of treating your phone as a limited viewing screen, it feels designed for the moments when you need a quick answer or a straightforward action. Checking whether a deposit arrived, looking over recent activity, or confirming that a transaction went through is much easier than waiting until you are back at a computer.
That convenience matters because banking questions often appear at inconvenient times. I can imagine using it at a store checkout to confirm available funds, after paying a bill to make sure the transaction appears correctly, or while splitting a restaurant bill and wanting to verify the account before sending money. These are small interactions, but they are exactly where a mobile banking app earns its place.
Connectivity shapes all of those moments. With a dependable mobile signal or Wi-Fi, screens load in a predictable way and the app feels responsive enough for routine tasks. When the connection is slow, the experience becomes less certain: waiting for account information feels more stressful than waiting for an ordinary social app because the information is financial and time-sensitive. I recommend opening the app before you are standing in a checkout line if you already know you will need to verify something important.
A useful habit is to separate checking from acting. First review the account details and recent activity, then decide whether you need to make a transfer or payment. This reduces the chance of repeating an action simply because the first screen took longer than expected. It is a small workflow change, but it is especially helpful when the network is inconsistent and you are unsure whether a request has completed.
Useful in short mobile sessions
The app suits people who prefer several brief visits rather than one long financial session. I found that a phone is particularly convenient for confirming a balance before a purchase, reviewing a transaction soon after it happens, or checking whether a scheduled money movement needs attention. Those quick checks are easier to fit between errands than a full desktop banking session.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
There is also a psychological advantage to seeing activity close to when it happens. A recent transaction is easier to recognize when you still remember where you were and what you bought. That makes the app more useful for spotting mistakes or unfamiliar activity than a monthly review alone. I would not treat a quick glance as a replacement for carefully reviewing statements, but it is a good first layer of awareness.
The mobile format does have limits. A phone screen is not ideal for comparing many transactions, planning a complicated financial change, or studying spending patterns across a long period. If you need room to inspect details side by side, a desktop browser or a dedicated budgeting tool can be more comfortable. The app is better at immediate banking decisions than at becoming a complete financial planning workspace.
One practical tip is to avoid doing complicated tasks while distracted. A bus ride, crowded shop, or airport queue may be where you reach for the app, but those environments make it easier to mistype information or lose track of which screen you were viewing. For a simple balance check, that is rarely a problem. For a sensitive transfer or account change, I would wait for a calmer moment and a stronger connection.
When a weak signal changes the experience
Financial apps cannot be judged only by how they behave on a perfect home network. In real life, I may open banking software inside a concrete building, underground transportation, or a crowded public venue where cellular service is unreliable. In those situations, the key question is not whether the app can magically avoid network limitations, but whether I can recognize what has happened and recover without guessing.
A stalled loading screen is more concerning here than in a news app. If I am checking a balance, I need to know whether I am looking at current information. If I am initiating an action, I need confidence about whether it was accepted. My advice is simple: when a request appears stuck, do not immediately submit it again. Give the screen time to respond, then check the relevant account activity before trying a second time.
This is one of the most important trade-offs in mobile banking. Speed is convenient, but certainty matters more. A fast connection makes the app feel effortless; an unstable connection turns the same task into a process that requires patience. Users who frequently bank from places with poor reception should build in a verification step after every important action rather than assuming that a button press tells the whole story.
Another sensible approach is to keep a mental note of the starting balance or the transaction you are trying to confirm. You do not need to record every detail, but knowing what you expected to see makes recovery easier. If the connection drops, you can later compare the account activity against that expectation instead of repeating the action from memory.
Recovering from interrupted sessions
Mobile banking sessions can be interrupted for ordinary reasons: the phone switches networks, another app takes focus, the device locks, or the connection briefly disappears. I prefer treating an interruption as a reason to restart the check carefully, not as proof that something failed. Reopen the app, authenticate again if required, and inspect the account activity before deciding what to do next.
This matters most for transfers and payments. A user who sees an error may be tempted to try again immediately, while a user who sees no confirmation may assume nothing happened. Either assumption can create confusion. The safer workflow is to look for evidence in the account history or the destination account, then proceed only when the status is clear.
The same principle applies when an app closes unexpectedly. I would not rely on a notification or a memory of the last screen. I would return to the account and review the latest activity. This may feel slower than pressing the same control again, but it is the more responsible habit for financial actions.
Authentication is another point where convenience and security meet. A banking app has to protect access, and that can make a rushed mobile session feel less smooth than opening a general-purpose app. I consider that a reasonable inconvenience. If you are repeatedly interrupted during sign-in, choose a stable location and avoid switching between networks while completing the process. Keeping the app updated is also sensible; the current version is 26.10.1.71 and requires at least iOS or Android version 12.
That operating-system requirement is worth checking before installing on an older phone. For people with a recent device, it should be a straightforward consideration. For anyone keeping an older handset for occasional banking, compatibility may decide whether this is the right choice before the banking features even matter.
Using it without wasting mobile data
Banking tasks usually involve less media than video or social apps, but data-conscious users can still make the experience more predictable. I would use a trusted Wi-Fi connection for longer account reviews or several actions in a row, while reserving mobile data for quick checks when necessary. This is not because the app should be treated as unusually data-heavy; it is simply a sensible way to avoid depending on a marginal signal at the exact moment you need reliable financial information.
Notifications and background activity are also worth considering as part of a personal routine. I prefer opening the app deliberately when I need to inspect an account rather than turning every financial moment into a constant stream of phone interruptions. On the other hand, someone who wants to notice activity quickly may value timely alerts. The right balance depends on whether you find notifications reassuring or distracting.
For privacy, I would avoid checking sensitive account details on an unsecured public network when a private connection is available. A coffee shop or hotel network may be convenient, but banking deserves the same caution as entering payment information on any other service. A strong device lock, current operating system, and careful attention to sign-in screens are more important than saving a few seconds.
One non-obvious benefit of a data-conscious routine is better concentration. If I wait until I have a stable connection for a complicated task, I am less likely to rush through it because a page is taking too long. That improves accuracy as much as it improves technical reliability. For simple balance checks, mobile data is convenient; for important changes, a calm setting and dependable network are the better combination.
Who gets the most from the app
This is a strong fit for an existing TD customer who wants ordinary banking within reach throughout the day. The app makes the most sense if your main needs are account awareness, routine money movement, and quick confirmation while away from a computer. Its free price also removes a common barrier for someone deciding whether a mobile banking companion is worth installing.
It is especially useful for people who manage money in short bursts: students checking funds before spending, families reviewing activity between errands, or workers who need to confirm a banking detail during a busy schedule. The Everyone age rating makes it broadly accessible, although younger users should still use appropriate supervision and account permissions where relevant.
I would be more cautious about recommending it as the only financial tool for someone who wants advanced budgeting dashboards, broad account aggregation, investment analysis, or detailed long-term planning. A dedicated budgeting app may offer better visual comparisons, while a desktop banking experience can be easier for complex reviews. The usual alternative is not necessarily better overall; it is simply better suited to a different job.
It is also not the ideal choice for someone who expects banking to remain fully comfortable in places with unreliable reception. The app can be convenient in mobile contexts, but connectivity remains part of the experience. If your daily routine regularly takes you through dead zones and you often need to make urgent financial decisions there, plan those tasks around a reliable connection rather than assuming the phone will always be ready.
How it compares with ordinary alternatives
Compared with visiting a branch, the app is faster for routine checks and less dependent on opening hours or travel. Compared with a desktop browser, it is more convenient when you are away from home but less comfortable for reviewing a large amount of information. Compared with a general budgeting app, it is closer to the source of your banking activity, while a budgeting specialist may be better at showing broader spending patterns.
That distinction helps prevent unrealistic expectations. I would choose this app when I need direct, everyday access to TD banking. I would choose a desktop session when the task requires careful reading and several steps. I would add a separate budgeting tool when the goal is understanding habits across accounts rather than simply managing one bank relationship.
The app’s scale is reassuring in a practical sense: it has been available since Aug 14, 2010, and its current release shows that it remains maintained for modern devices. Still, longevity and popularity do not remove the need for personal testing. Your device, connection, sign-in experience, and banking needs will determine whether it feels dependable in the situations that matter to you.
My final view on connectivity and convenience
After using it as a mobile finance tool, I see TD Bank as a sensible choice for customers who want everyday banking close at hand. Its best moments are quick and purposeful: checking activity, confirming a balance, or handling a routine task while away from a computer. The experience becomes less comfortable when the network is weak or when the task is complicated enough to need a larger screen.
The most important habit is to verify important actions instead of repeating them when a connection hesitates. That single step makes the app safer to use in real mobile conditions and prevents uncertainty from turning into duplicate work. I would also keep complex banking for a stable connection, use public networks cautiously, and treat the phone as a convenient access point rather than a full substitute for every financial tool.
With an average rating of 4.2 and more than 5 million installs, it is clearly a well-established option, but my recommendation is still specific: choose it if you are a TD customer who values quick access and can usually bank with dependable connectivity. Skip it as your main solution if you need deep budgeting analysis, broad multi-bank management, or frequent urgent use in poor-signal locations. For the everyday banking role it is built around, the balance between convenience and connection awareness feels reasonable.
Frequently Asked Questions
01What is TD Bank, and what can I do with its mobile app?
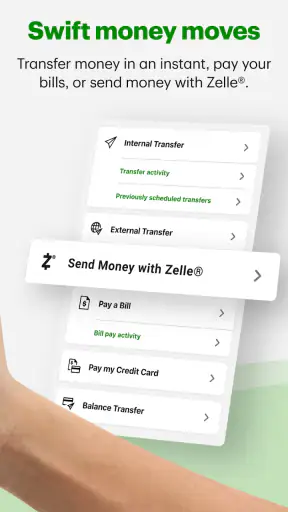
TD Bank is a U.S. banking app for managing eligible personal and business accounts from an Android or iOS device. After signing in, customers can typically check balances, review transactions, transfer money, pay bills, deposit eligible checks, manage TD credit cards, locate branches and ATMs, and contact customer support. Available tools may vary depending on the account type and current TD Bank policies.
02Is the TD Bank mobile app safe to use?
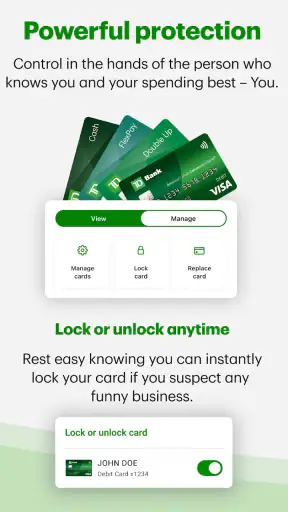
The TD Bank app uses security features designed to protect your banking information, including encrypted connections, secure login procedures, device verification, and optional biometric authentication such as fingerprint or Face ID. However, no banking service is completely risk-free. Download the app only from the official Google Play Store or Apple App Store, keep your device updated, avoid public Wi-Fi for sensitive activity, and never share verification codes.
03Can I deposit checks using the TD Bank app?
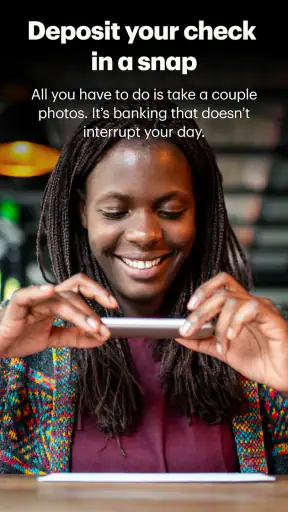
Eligible customers can generally deposit checks through the app’s mobile deposit feature by photographing the front and endorsed back of the check. The images must be clear, and the check should meet TD Bank’s acceptance requirements. Deposit limits, availability of funds, processing times, and restrictions can vary by account and customer. Keep the original check safely until the deposit is confirmed and no longer subject to review.
04Does the TD Bank app charge fees for transfers, bill payments, or mobile deposits?
Many standard services available through the TD Bank app, such as viewing accounts, paying eligible bills, and making certain internal transfers, may be included with your account. Nevertheless, fees can depend on the transaction, account type, transfer method, overdraft settings, or the financial institution receiving the money. Review the fee information shown in the app and your account agreement before completing an unfamiliar transaction.
05What should I do if I cannot log in or notice suspicious activity?
If you cannot access your account, first verify your username, password, internet connection, and app version, then use TD Bank’s official recovery options rather than links received through unexpected messages. If you see an unfamiliar transaction, lost your phone, or suspect that your credentials were exposed, contact TD Bank immediately through an official website, app, or phone number. Avoid responding to requests for passwords, PINs, or one-time security codes.


